Zimbabwe Looks to India to Lower Transfer Costs and Speed Payments
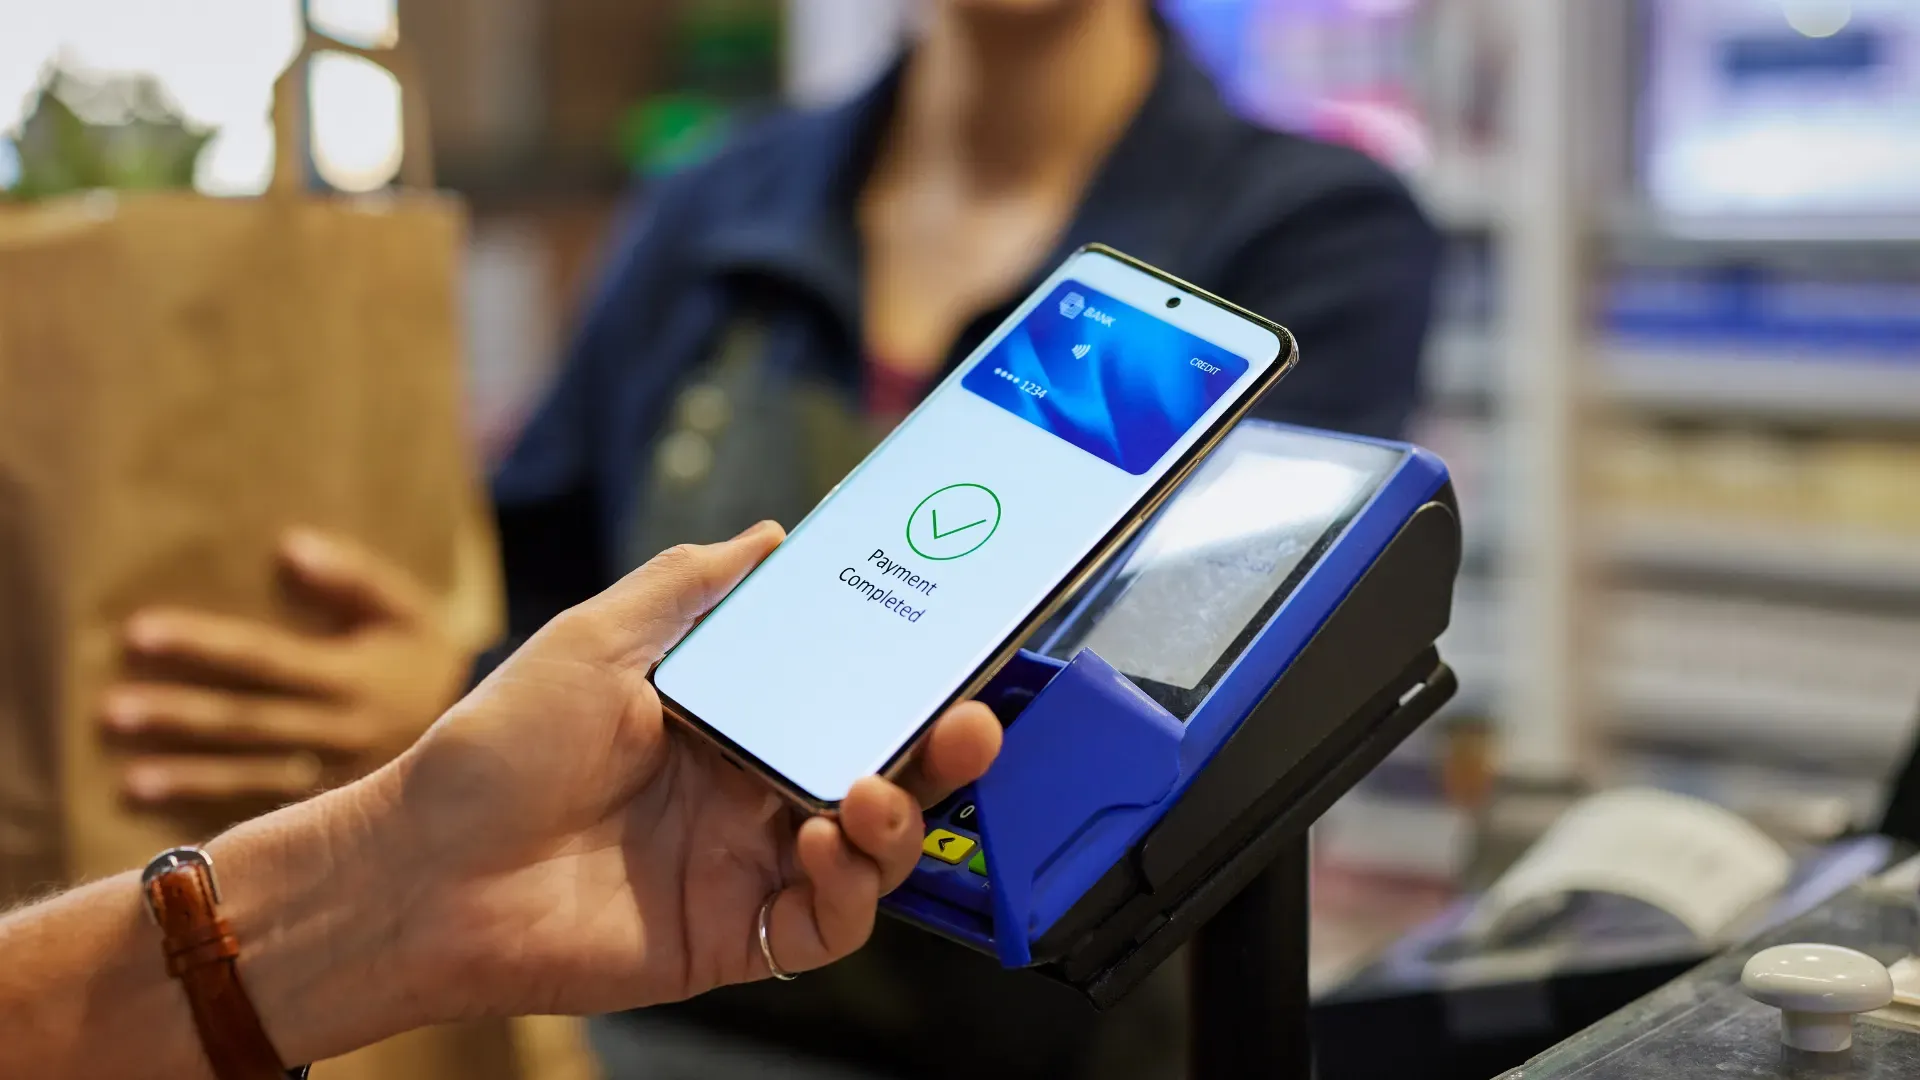

Zimbabwe is now in discussions with NIPL to explore technology that works like India’s Unified Payments Interface (UPI). The negotiation process will be between the international wing of the National Payments Corporation of India.
It will help develop a common infrastructure that will be used by banks, mobile money service providers, fintech firms, and other payment providers.
Transactions from one provider can easily flow to another provider in real-time.
Reserve Bank of Zimbabwe Governor John Mushayavanhu said in an interview with Bloomberg that discussions between Zimbabwe and NPCI International Payments Ltd could be concluded by 31 October. It is just a deadline for concluding talks and not for launching the UPI technology.
“The talks with NPCI International Payments Ltd could conclude by October 31,” Mushayavanhu told news sources.
Zimbabwe targets fragmented payments network
This partnership follows Zimbabwe's efforts to ensure interoperability within its payments ecosystem.
RBZ has made strides in making QR payments in line with interoperability requirements. In March 2026, the RBZ issued a circular compelling all banks and payment service providers to adopt the new QR standards for payments.
According to the RBZ, the requirement is set to ensure interoperability in QR payments among banks, mobile money service providers, and other payment service providers. This will prevent fragmentation in the system where QR payments can only be carried out using specific platforms.
Additionally, QR standards require all payment service providers to offer QR payments in mobile applications, USSD, Point of Sale, and web platforms. The QR payment standards are based on the EMVCo QR standards for payment interoperability.
Therefore, the NIPL partnership is more than just launching another payment app within the country’s payment ecosystem.
Lower costs are a key objective
For consumers and businesses, the main appeal is likely the prospect of lower fund-transfer costs.
The common account-to-account system can lower the reliance on card technology for certain low-value domestic transactions. In addition, banks could provide merchant payment services at reduced cost.
Mushayavanhu also said the technology can enable the creation of innovative financial instruments. Improved data on digital payments can help regulators get better insights into the transactions of small and medium-sized businesses.
However, lowered transaction costs cannot be expected just because the UPI technology is implemented. The final savings will depend on the manner in which the technology will be used.
Pricing, financial institution involvement, investments and business agreements will all play a role in the final cost for consumers and businesses.
Cross-border payments could become a longer-term opportunity
Zimbabwe could eventually look beyond domestic payments.
The country has a large diaspora that sends money home. Faster and cheaper digital channels could therefore have implications for remittances and cross-border transfers.
But cross-border payments would require additional agreements between countries, payment providers and regulators. The initial focus appears to be on building domestic payment infrastructure.
This distinction is important. Zimbabwe would be exploring the underlying technology behind UPI rather than simply allowing Indian consumers to use UPI at Zimbabwean merchants.
That model could give Zimbabwe greater control over its own national payments infrastructure.
India’s payments technology is already expanding in Africa
Zimbabwe is not the first African country to work with NPCI International.
In May 2024, NPCI International signed an agreement with the Bank of Namibia to support the development of an instant-payment system based on the UPI model. The initiative was designed to improve payment interoperability and support faster transfers and merchant payments.
The Namibian agreement shows how India is increasingly exporting its payments infrastructure model rather than only expanding the use of UPI among Indian users overseas.
UPI itself has grown rapidly since its launch in India in 2016. By August 2026, 752 banks were live on the system, while monthly transactions reached about 24.5 billion, according to figures reported by Moneycontrol. UPI accounted for roughly 49% of global real-time payment transaction volumes in 2025, based on Indian government data.
For Zimbabwe, the appeal is therefore not only the technology’s speed. It is the scale and interoperability that have developed around the Indian system.
Agreement would be only the first step
The immediate milestone is whether Zimbabwe and NIPL can conclude negotiations by the end of October.
Any agreement would still need to be followed by decisions on technical design, participating institutions, regulation, investment and pricing.
Zimbabwe’s existing QR reforms could provide part of the regulatory foundation. But connecting banks, mobile-money operators and fintech platforms at national scale would require broad participation.
If the partnership moves ahead, its success will ultimately be measured less by the adoption of UPI technology and more by whether Zimbabweans can move money between providers faster, more reliably and at a lower cost.